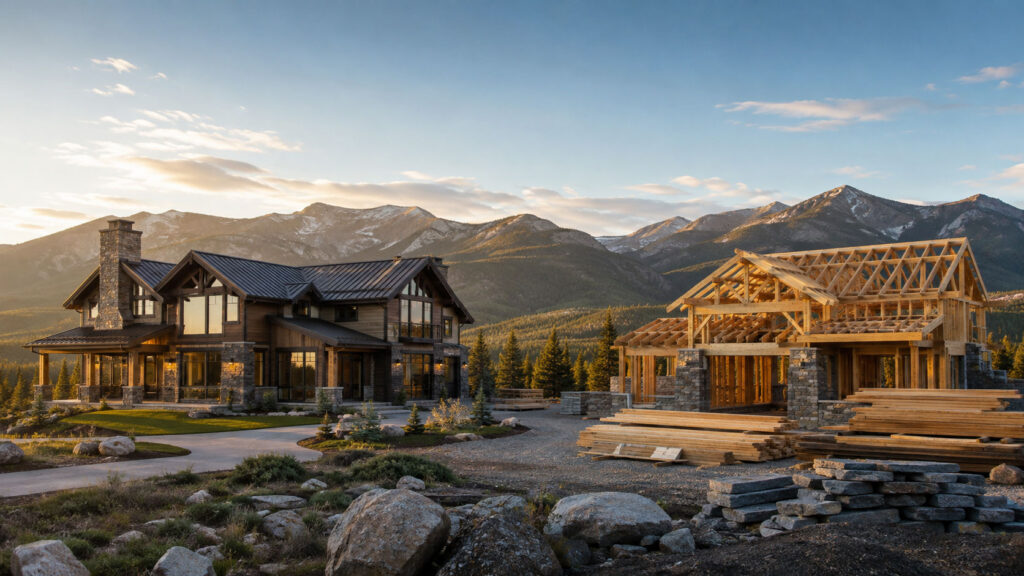
A rising real-estate market gets attention, but the number that matters after a major loss is what it costs to rebuild the home from the ground up.
SEO title: Home Replacement Cost vs. Market Value in Western Montana
Meta description: Learn why replacement cost differs from market value and how Western Montana homeowners can check dwelling limits before a major claim.
Suggested URL: /replacement-cost-vs-market-value-western-montana/
Keywords: replacement cost Western Montana, dwelling coverage, insurance to value, home reconstruction cost, Bitterroot Valley
One of the most common insurance misunderstandings is assuming that a home should be insured for its purchase price, tax value or expected sale price. Those numbers matter in real estate, but they do not answer the insurance question: what would it cost to reconstruct the house after a total loss?
Replacement cost focuses on labor and materials needed to rebuild a structure of similar kind and quality at the same location. Market value includes the land, location, acreage, views, supply and demand, and other factors that may not be damaged in a fire. Depending on the property, replacement cost may be higher or lower than market value.
Why Western Montana properties require a closer look
Rebuilding in the Bitterroot Valley or another rural Western Montana community can involve costs that a simple square-foot estimate misses. Contractors and specialized trades may have to travel. Materials may carry freight costs. Driveways, slopes, winter conditions and limited staging space can slow work. Debris removal after a wildfire can be unusually expensive, and updated building codes may require changes that were not part of the original home.
Custom finishes create another challenge. Log construction, timber framing, stonework, custom cabinetry, outbuildings and older craftsmanship are not interchangeable with standard tract-home assumptions. A replacement-cost estimate is only as good as the property information entered.
Five policy details to review
Dwelling limit. This is the starting amount available to rebuild the insured home. Ask when the replacement-cost estimate was last updated and verify square footage, construction type, quality grade and major features.
Extended replacement cost. Some policies provide an additional percentage above the dwelling limit when reconstruction costs exceed the estimate after a covered loss. This is valuable protection, but it has conditions and is not unlimited.
Ordinance or law coverage. This can help pay the added cost of rebuilding to current codes when those upgrades are triggered by a covered loss. Older and significantly remodeled homes deserve particular attention.
Debris removal. Removing damaged material, trees and hazardous debris can consume part of the policy limit or be subject to a separate allowance. Ask how your policy responds.
Other structures and contents. Detached garages, shops, barns, fencing and personal property have separate limits and definitions. A standard percentage may not fit an acreage property, hobby farm or home-based business.
When to update the estimate
- After an addition, major remodel, finished basement or new garage/shop
- After installing custom cabinetry, premium flooring, stonework or other high-cost finishes
- When the policy has not had a detailed replacement-cost review in several years
- When local construction costs or access conditions have changed
- Before changing carriers, so quotes are compared using consistent property details
A useful rule: Do not pick a dwelling limit only to reach a preferred premium. Start with a reasonable reconstruction estimate, understand available replacement-cost extensions, and then choose deductibles and optional coverage deliberately.
A review is more than changing one number
Increasing Coverage A without checking the rest of the policy may leave gaps. Many related limits are percentages of the dwelling amount, while endorsements can alter roof settlement, water damage, matching, ordinance or law, and other claim provisions. A complete review connects the property details, reconstruction estimate and policy language.
Sapphire Peak Insurance can help you review the assumptions behind your dwelling limit and compare how different carriers handle replacement cost. The goal is not to promise that every loss will be covered—policy terms, exclusions and claim facts always matter—but to reduce avoidable surprises before a claim happens.
Sources and further reading
• Montana Commissioner of Securities and Insurance: Home insurance information
• Montana Commissioner of Securities and Insurance: Rising costs and wildfire risks
This article is for general educational purposes and is not a coverage determination or legal advice. Insurance availability, eligibility, discounts and coverage vary by insurer and policy. Refer to the actual policy and endorsements for terms, conditions, limitations and exclusions.