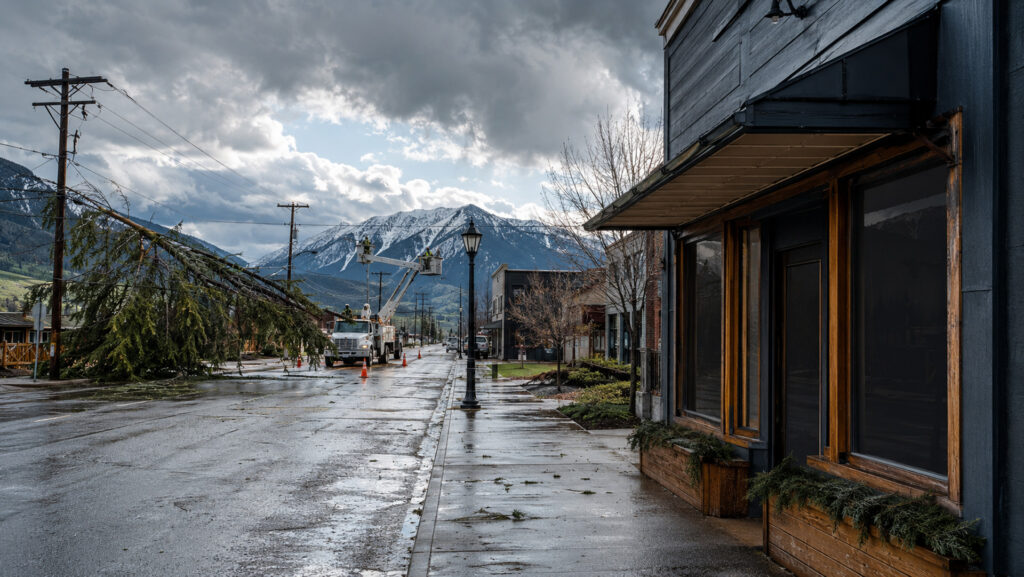
When the building survives – but the business still cannot operate
The December 17, 2025 windstorm delivered a powerful reminder that Western Montana businesses face more than wildfire risk. Hurricane-force winds, falling trees, damaged utility infrastructure and extended power outages affected communities throughout the region.
According to NOAA, wind gusts reached approximately 87 mph in the Missoula and Bitterroot valleys, while some mountain locations exceeded 100 mph. The storm produced an estimated $2.3 million in reported property damage, and some utility customers remained without power for more than a week. Grocery stores and other businesses also experienced spoilage and operational losses during the outages.
Source: NOAA Storm Events Database
Property insurance may not replace lost income
A commercial property policy can help repair covered damage to a building, equipment or inventory. However, it does not automatically mean every interruption-related expense will be covered.
- Business income coverage: Replaces qualifying lost income when covered physical damage forces the business to suspend operations.
- Extra expense coverage: Helps pay reasonable additional costs incurred to continue operating or reopen sooner.
- Utility services coverage: May address losses caused by damage to off-premises electrical, water or communication systems.
- Equipment breakdown coverage: Can cover certain mechanical or electrical failures that ordinary property insurance may exclude.
- Spoilage coverage: Particularly important for restaurants, grocery stores, pharmacies and businesses with temperature-sensitive products.
- Civil authority coverage: May apply when a government order restricts access because of nearby covered property damage.
Each coverage contains triggers, exclusions, limits and waiting periods. A power outage by itself does not necessarily activate business-income coverage.
Three questions every business should answer
- How long could we operate without electricity, internet or water?
- How much income would we lose during a three-day, seven-day or 30-day shutdown?
- Does our insurance cover interruption caused by off-premises utility damage?
Businesses should also document major equipment, maintain updated inventory records and keep copies of financial information somewhere other than the insured premises. These records can be extremely important when calculating a business-income claim.
| The takeaway: A business does not have to burn down to suffer a serious financial loss. A tree across a power line, an inaccessible road or a prolonged utility outage can be enough. |
Sapphire Peak Insurance can help Western Montana business owners review their property, business-income, equipment-breakdown and utility-service coverage before the next severe-weather event.